






The Uncertain Nature of Risk: Challenging Traditional Investment Assumptions
Traditional investment strategies often rely on historical data and specific models that assume predictable risk. However, recent studies reveal the dynamic and unpredictable nature of risk, highlighting the need for re-evaluation. By examining real-world scenarios and experimental setups, this article questions established assumptions in investment decision-making. It suggests moving beyond static models to embrace a more fluid understanding of risk that incorporates complexity and non-linear dynamics, urging a shift in how investors approach uncertainty.

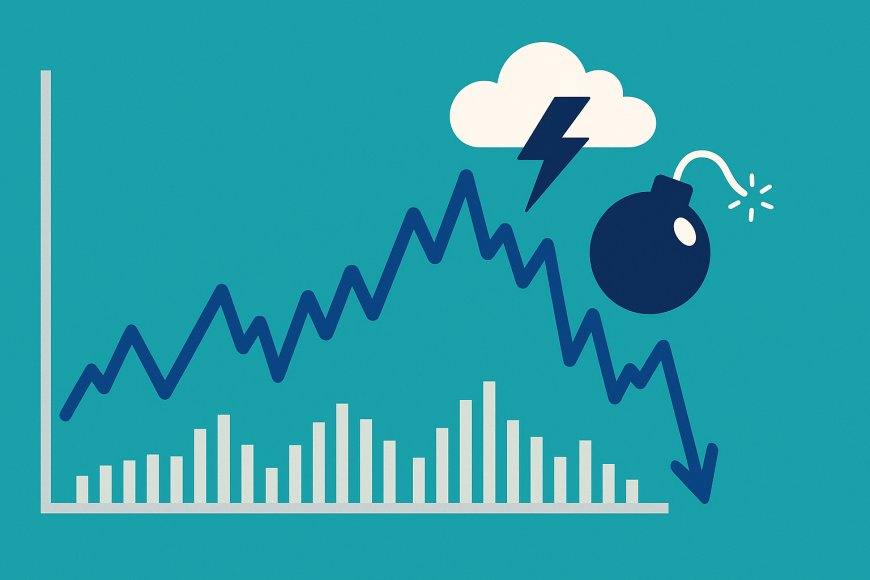
In a typical investment scenario, advisors often rely on historical data and established models to predict risk. This approach presupposes that risk is a quantifiable element—one that can be measured, predicted, and managed through statistical analyses. Yet, empirical evidence increasingly suggests that such assumptions may not fully capture the complexity of financial markets.


Consider a recent observational study conducted by a prominent financial institution. Analysts examined market behavior during an economic downturn, comparing it to historical patterns. Surprisingly, the anticipated correlations between past downturns and current market responses were not as robust as traditional models predicted. This illustrates the inherent unpredictability and dynamic nature of financial risk, challenging the belief that past data can be solely relied upon to forecast future market movements.
Reimagining Risk in Investment Decision-Making
Traditional risk assessment models often assume a linear relationship between variables, a premise grounded in classical economic theory. These models typically depict markets as rational, where investors act in predictable ways based on available information. However, real-world financial landscapes rarely conform to such orderly frameworks. Non-linear dynamics, characterized by abrupt changes and feedback loops, are now seen as integral to understanding market behaviors.
For instance, an experimental setup at a leading university tested these principles by simulating market scenarios with diverse variable interactions. Participants, acting as investors, were placed in environments where financial events unfolded unpredictably, illustrating how market actors' decisions contribute to non-linear risk patterns. The experiment showed that investors often rely on heuristics, leading to decisions that defy traditional rational models.
This paradigm shift suggests the necessity of incorporating complexity science into financial risk assessment. By recognizing that market behavior emerges from the interaction of numerous, often unpredictable elements, investors can better anticipate and navigate the uncertainties inherent in financial systems.
Beyond the Bell Curve: Embracing Complexity
Conventional financial models frequently utilize the bell curve to represent risk probabilities, an approach that assumes normal distribution of data. The bell curve implies that most outcomes will cluster around a central average, with extreme events being rare. However, market crashes tell a different story, often defying these statistical assumptions.
A behavioral experiment conducted by a consortium of economists examined market responses to unexpected geopolitical events. The findings revealed that extreme outcomes were more common than the bell curve predicted, suggesting the presence of "fat tails" or a greater likelihood of outlier events than classical models account for. This points to the necessity of adopting broader statistical methods that better capture the true range of financial risk.
Such insights advocate for a methodological overhaul, urging the integration of concepts like fractals and chaos theory into risk assessment protocols. By doing so, investors can achieve a more nuanced understanding of market volatility, moving beyond simplistic, deterministic models.
Adaptive Strategies for Uncertain Times
In response to these evolving insights, financial strategists are increasingly advocating for adaptive investment strategies that emphasize flexibility and resilience. Adaptive systems, characterized by their ability to learn and evolve, offer a promising framework for managing unpredictable market conditions.
The adoption of machine learning algorithms, which can process vast datasets and identify complex patterns, exemplifies this shift toward adaptability. In a simulated trading environment, these algorithms demonstrated enhanced accuracy in predicting market movements by learning from both historical data and real-time inputs. Their ability to adjust strategies based on emerging trends highlights the potential for more responsive investment approaches.
Yet, the implementation of such technologies is not without challenges. Questions about data integrity, algorithmic bias, and ethical implications remain significant. Nonetheless, the integration of adaptive strategies signifies a move toward reconciling the inherent uncertainties of financial markets with innovative, data-driven solutions.
As we move forward, the recognition of risk's uncertain nature compels investors to re-evaluate established paradigms. Embracing complexity and adaptability will be crucial in navigating the unpredictable financial landscapes of the future.
What's Your Reaction?